EVERYTHING’S A SCAM
Why You’ve Probably Never Heard of “American Income Partnerships” Before…
And How You Can Use Them to 6X-8X Your Dividend Income
Dear Friend,
Is it me, or does it feel like everything’s a scam these days?
It literally starts the moment I wake up. And it doesn’t stop until I go to bed.
Emails that look like they’re from my bank. They’re not. Click the link and somebody in another country is inside my checking account.
Phone calls from numbers that look oddly familiar. My car warranty ran out. My "account" has been locked. All fake.
Texts from "Amazon" about a package I never ordered.
But what really burns me is shopping for groceries. Every week is a fresh insult.
Food companies charge you twice the price for half the food…
Beef that costs over $11 a pound…
Eggs that are so expensive they’ve become their own asset class.
But as bad as all that is, nobody does it bigger than Wall Street.
The 2008 real estate crash and mortgage crisis proved that.
First, they got bailed out in 2008 during the mortgage crisis.
Then they turned around and bought back all the same houses that caused the crisis in the first place.
Only to rent them back to us, turning a whole generation of Americans into permanent serfs!
Even now as I write this I feel anger.
Here’s what 35 years in this business has taught me: These people don’t give a hoot about us.
They only get paid when you buy or sell. Not when you win.
That’s why I haven’t taken a stock recommendation from them for decades.
They’re also the last place I now look to for advice on income investing.
Ever since I turned 50, I’ve begun to hunt for income investments. Safe investments with great yields.
Easier said than done.
They want to sell us packaged income products with upfront sales fees as high as 7%.
And if we don’t want that, the best they can do are “Dividend Aristocrats” with pitiful 1% yields.
But they offer their richest client’s opportunities you can’t even imagine.
One of which is a small group of what I call “American Income Partnerships.”
Some of the richest investors in America use them to boost their monthly income.
Leon Cooperman has collected an average of $1.5 million a month in payouts during the first eight months of this year — and the next check lands in November.
David Tepper has collected an average of $177,000 a month in payouts in the first eight months of the year.
Mario Gabelli has collected an average of $38,000 a month - roughly $1,250 a day - of payouts in the first eight months of the year.
In a moment, I’m going to show you how to design a calendar that allows you to collect 12 checks a year from them. One every month.
Here’s what that year looks like:
Every one of those twelve is a real company. You’ll meet the first two in a minute.
But first, here’s why you should listen to me:
My name is Dylan Jovine.
Now, what I’m saying to you may sound optimistic. And maybe you doubt that I can deliver, which is fine.
But please know that people doubted me when I predicted the Great Recession and market crash a year before it happened.
“The market has no place else to go but down. It’s not a question of ‘if’ it’s a question of ‘when.’”
A year later, the S & P 500 dropped 43%...
They doubted me when I predicted a big stock rally during the height of the Covid panic…
“FACT: When we get to the other side of this, the market will have a “SNAP-BACK” rally because prices and interest rates are so cheap.”
Six months later, the market was up 60%.
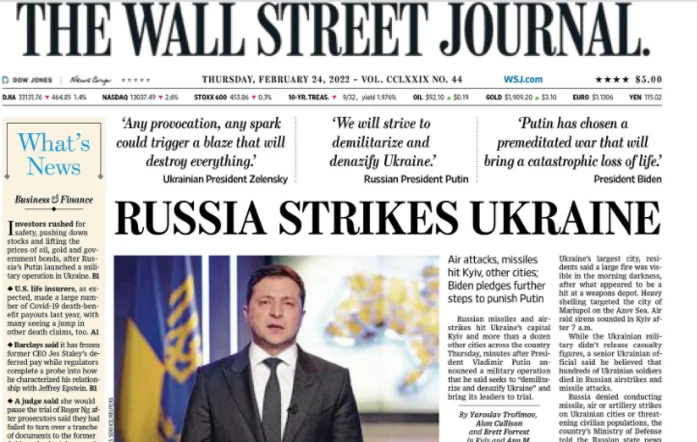
When in July of 2021, I predicted Russia and China would bring the world into a new cycle of war.
“The world is entering a new cycle of war. Russia and China are trying to flip the international script just like Germany did in 1914.”
…just seven months before Russia invaded Ukraine.
When in 2022, I predicted that inflation would last longer than expected.
“The FED wanted you to believe that inflation was just “transitory.” But inflation doesn’t work that way. I’ve looked at data going back to 1929. It has never once showed up for just one year.”
A lot of people laughed at me when I made these predictions.
They didn’t think a kid who grow up dirt poor and went to city college could ever know more than the “Elites.”
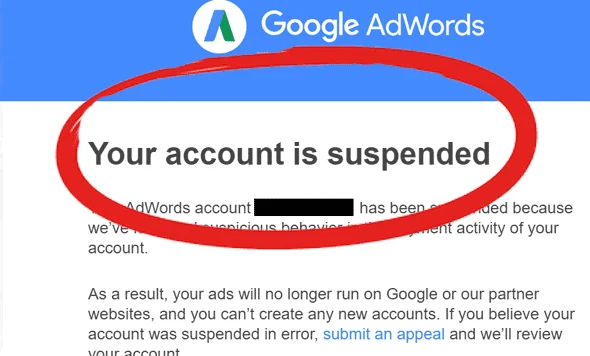
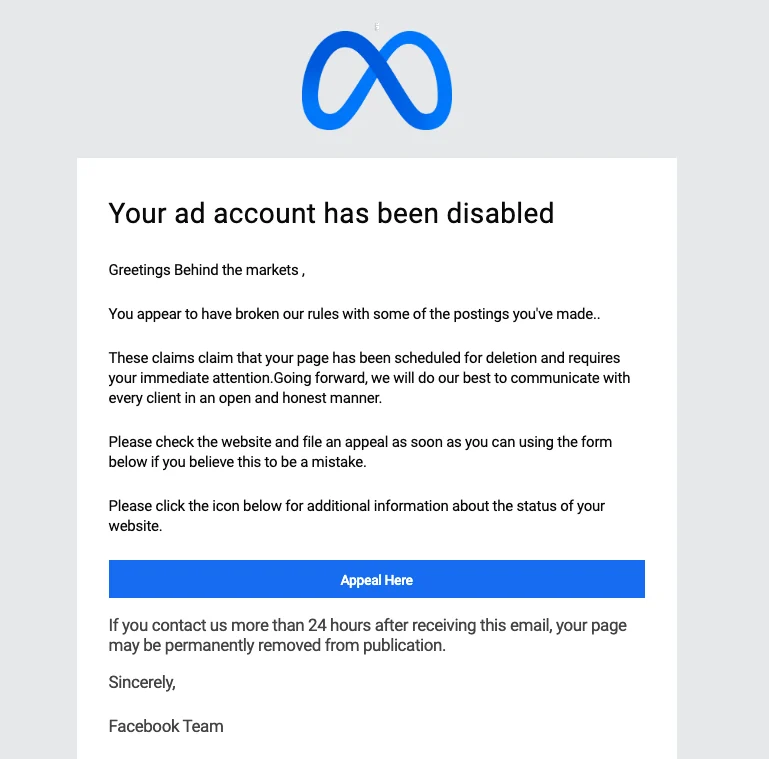
Both Google & Facebook suspended my accounts.
And even the Chinese Communist Party sent a woman to talk to me when I began to warn people that China would invade Taiwan.
But despite the risks to my business, I didn’t let any of them stop me from getting you the truth.
I fought on to keep bringing you the most important financial stories nobody else was talking about.
And I’ll never stop.
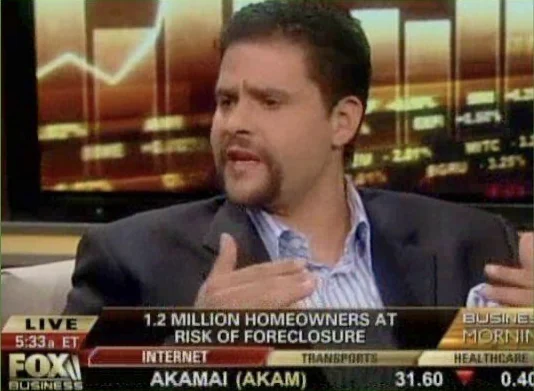
In the wake of predicting the real estate collapse a year before it happened, I was interviewed by Fox Business…
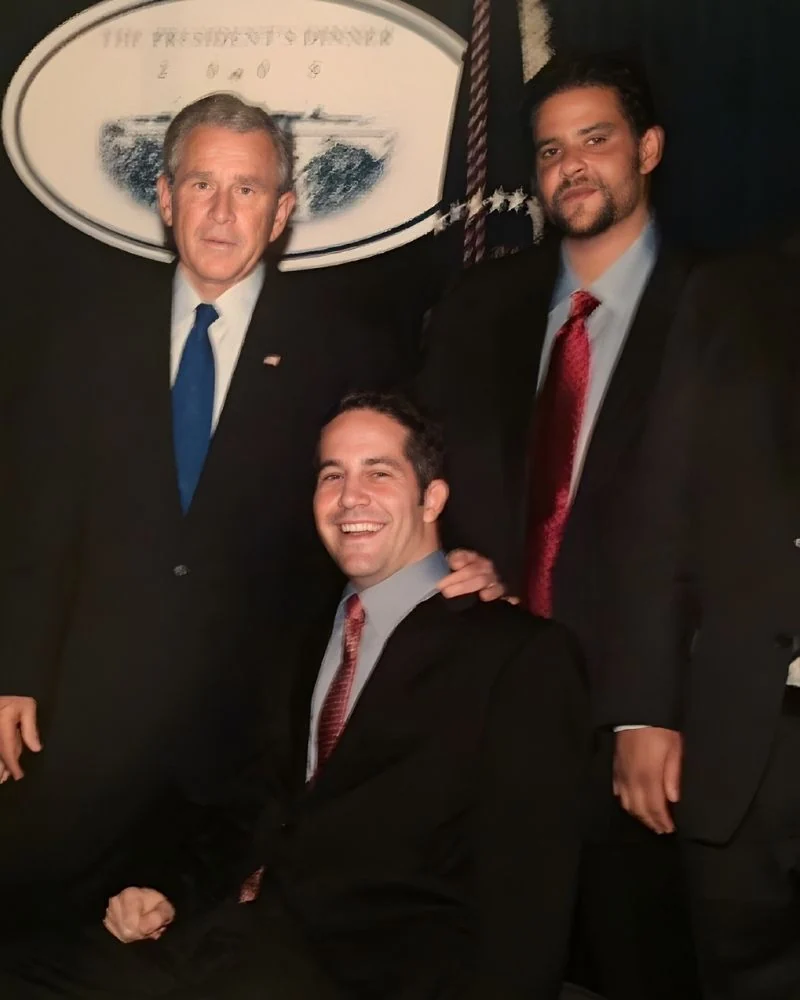
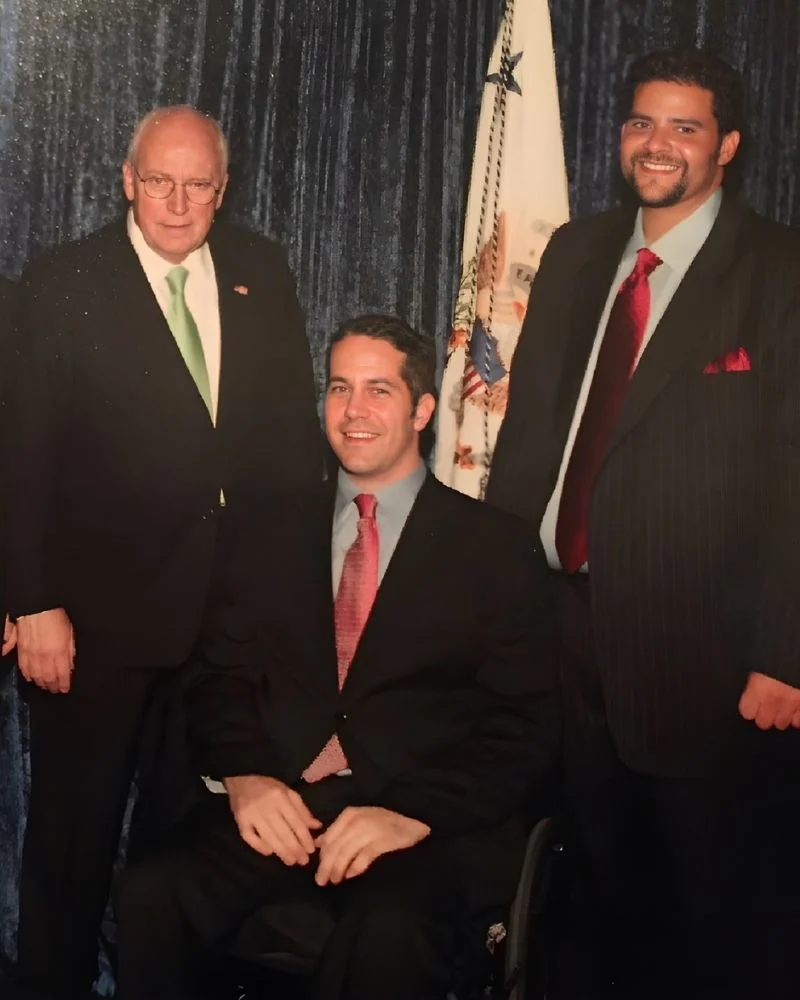
And then I was invited to Washington, D.C. to meet President George Bush and Vice President Dick Cheney.
One last note before we begin this presentation.
I may be known around the world for making bold and timely predictions.
But today, I write to you today as an American first.
We are facing a retirement crisis in this country, and I feel compelled to try to help.
Almost nobody on Wall Street will tell you about American Income Partnerships. There’s nothing in it for them.
So how exactly do American Income Partnerships work?
Built to Distribute Cash
Here’s what makes American Income Partnerships so different...
And it might get you a little fired up, if you’ve been burned by stocks before.
Each one is built to send cash to their partners every ninety days. Own a handful with different pay dates and you get a check every single month.
That’s a new check every 30 days. Year after year.
You read that right. The stock market can go up, down or sideways. The checks come anyway.
Let me show you. Say you turned on the news back in 2019 and heard that America was about to pump more natural gas than any country on earth.
So you bought Chesapeake Energy. One of the biggest gas drillers in the country. A stock Carl Icahn himself once owned 13 million shares of.
Big mistake.
In June of 2020, Chesapeake went broke. The stock was wiped out. $10,000 didn’t turn into $5,000. It turned into zero.
That hurts.
But here’s the part nobody on TV told you.
Right up until the end, Chesapeake was sending a check every month to another company.
That other company is an American Income Partnership. It doesn’t have shareholders. It has partners.
Here’s what it looks like...
While Chesapeake’s owners lost everything, the company Chesapeake was paying sent its partners a check every three months. It never missed one.
So instead of losing $10,000... a $10,000 stake in this company paid you about $5,000 in cash over the same stretch. And you still own it.
Tell me which you’d rather have...
A "hot" stock that went to zero?
Or a boring company that got paid by the hot stock — and passed the money on to you?
To me, that’s not even close.
But most people never get to choose.
They’ve been trained by TV and Wall Street to think stocks, stocks, stocks. All day long.
They even follow the rich guys on TV.
Look at what happened with one of my investing heroes, Warren Buffett.
A few years ago, word got out that Buffett’s company had bought a big piece of Paramount.
And I heard the same thing from everyone: "Dylan, if Buffett’s buying it, it must be good."
My answer? "Fine. Let him."
Buffett has hundreds of billions of dollars. If he’s wrong on one stock, he doesn’t feel it. If you’re living on your savings, you feel every dollar.
I’ve watched it for 34 years. Good people following a famous name right off a cliff.
That’s just what happened here.
The stock lost more than half its value. Then the company cut its dividend by 79%. Buffett himself later said it was a mistake. He sold at a loss.
Now look at a second American Income Partnership, over the same years...
It paid about $4,200 in cash on a $10,000 stake. And it raised the payment every single year.
I don’t know about you, but I can’t afford to lose half my savings on one bad stock. I bet you can’t either.
The good news is, you don’t have to. I’ve found a whole group of these partnerships. Own the right ones and you could get a check every month of the year.
But before I hand you the names, there’s one thing I need from you first...
Toss Out the Junk They Put in Your Head!
Here’s the one thing I need from you.
Stop listening to the people on TV whose job is to keep you trading.
Guys like that hand out a fresh half-cooked stock tip every single day. It’s a legal version of the same old game. It’s not advice.
And look, I get why people watch. It’s fun.
So is the guy at the fair who bets you can’t find the ball under the cup.
Next time you see one of these clowns on TV, I want you to do one thing. Laugh. Then change the channel.
Because that’s all they deserve.
They’re paid to be there. Same as the brokers pushing those 7% fee products. Licensed. Legal. And working for someone else.
That’s just how it is.
So before I hand you these partnerships, I need to know you won’t get pulled back in by the noise.
And here’s the thing — once you see how this works, I don’t think you’ll miss the noise at all. It beats losing money on stocks and options by a mile.
Money that shows up every three months, from companies that have to get paid, beats a hot tip every time.
Because when this market finally rolls over, the folks with the hot tips are the ones who get hurt.
The Most Expensive Stock Market in History
Here’s the plain truth. If you’re putting money into stocks right now without looking, you’re playing with matches in a dry field.
Not long ago, The Wall Street Journal reported that dozens of well-known companies now pay out more in dividends than they earn.
People pile into those stocks because they think a dividend means safe. It doesn’t.
Many of these companies carry huge price tags with no profits to back them up.
Right now, the whole market costs about twice what it has, on average, for the last 100 years.
We’ve already blown past the 1929 peak. There’s only one time in history it was higher. Right before the dot-com bust.
And the man Wall Street calls the greatest investor alive? Warren Buffett is sitting on more cash than he has ever held. Over $350 billion. He can’t find stocks worth buying.
$350 BILLION AND WAITING
Here’s what the numbers say...
Stocks cost about twice their normal price compared to profits. Dividends pay about half of what they used to.
Compared to sales, stocks cost more today than at any time on record.
The last time prices got this stretched was the dot-com bubble. On some measures, we’ve now passed even that.
I remember that crash well. I was on Wall Street when it hit.
This feels the same.
Even the big firms are saying it out loud. Goldman Sachs told its clients to expect stocks to earn about 3% a year for the next ten years. Three percent. From a firm that sells stocks for a living.
Palantir is a perfect example.
Its price is more than 400 times its profits. That’s not a typo. The average stock trades near 25.
Do you really think it can go up another 1,000% from here?
And I’m no Palantir hater. I told my readers to buy it at $8. We sold at $37 for a 362% gain. But at 400 times profits? Not with my money.
Now look at what one of my American Income Partnerships paid out over that same stretch — without anyone having to guess what a software stock is worth.
Or take Tesla.
It’s worth over $1 trillion. Its profits are falling. And it costs about 200 times what it earns. Eight times the market.
It’s already up thousands of percent. Do you really think it keeps climbing while its profits shrink?
Why bet on it? Not when one of these income partnerships over the same time...
...paid out about $1,000 in cash. On schedule. Every 90 days.
Here’s one more name you know...
Nike. The biggest sneaker company on earth.
In June of 2024, the stock lost 20% in one day. One day. Because it said sales might slip a little.
Let that sink in. The company still sold billions of dollars of shoes. And Wall Street took one-fifth of its owners’ money in a single afternoon.
That’s the stock market for you. You never know when one headline will reach into your pocket.
Does that sound like investing to you? Or a casino?
Counting that drop, Nike has lost 62% of its value. That’s $6,200 gone on a $10,000 stake.
But folks in American Income Partnerships didn’t lose a dime on Nike.
Instead, they collected about $1,600 over the same time. From partnerships that get paid whether sneakers sell or not.
Nobody had to guess. The checks were on the calendar.
Now here’s something important. Because I don’t want you mixed up about what I’m doing.
This Is Not About Betting Against Stocks
I am not telling you to bet against stocks.
Yes, I just showed you a few high flyers that could fall hard and fast.
But I’m not going to tell you to short them. That’s a fool’s game too.
The nice thing about the way we do it is simple. It pays whether stocks go up, down or nowhere at all.
Take Disney.
As I write this, it’s down about 8% over the past year.
But that number won’t sit still. It swings so much that by the time you read this, it could be up, down, or somewhere in between.
Just look at the ride.
Now think about the sure thing instead. My way.
One American Income Partnership paid about $700 over the same year. No ride.
Or take Starbucks.
You’d ride every up and down in the news to end the year about where you started.
Or you could skip the drama, own the partnership, and collect about $700 in cash.
And yes, this works even when a stock goes to the moon.
Look at Nvidia. One of the best stocks of the last five years. Up about 900%.
And what did Nvidia pay its owners in cash last year? On a $10,000 stake, about three dollars. Three.
This income partnership paid about $700 over the same year. And it did it the same way it always does. On time, every three months.
The check came whether Nvidia kept going up or not. It had nothing to do with Nvidia.
Same story with Walmart.
A monster run. Up about 110% in two years. Can it keep climbing? Your guess is as good as mine.
I don’t have to guess. One income partnership paid out about $700 while Walmart did its thing.
You can see where I’m going with this...
It’s the best of both worlds. Up market, down market, flat market. It doesn’t matter.
Folks who own American Income Partnerships get paid.
So far I’ve shown you nine examples. Add them up and a $10,000 stake in each would have handed you more than $15,000 in cash. And I’ve got a lot more where those came from.
Every one of those checks was paid on the day it was promised. Not one of them was late.
So why isn’t everyone on Main Street doing this?
Simple. It’s the thing I hate most about this business...
There’s No Money in It for Them!
You see, nobody teaches this. Not in school. Not on TV. Not at your bank.
You won’t see American Income Partnerships on the front page of the paper. You won’t hear the words on the morning money shows.
I’ve looked. Go to any big money website and type in "income partnership." Good luck.
But here’s the part that really burns me...
Ask your broker about them and watch what happens. He’ll change the subject. Or he’ll smile and say, "That’s a bit much for most folks."
There’s a reason he does that. And it stinks.
There’s no payday in it for him.
When you buy something and sit on it for 20 years, nobody on Wall Street gets paid again. Not once.
No bonus. No prize trip. No pat on the back from the boss.
And the big funds? Most of them are only allowed to put a small slice of their money here. It’s written right into the tax rules. So they don’t bother.
The hotshot in the corner office chasing his next Porsche has no reason on earth to bring this up.
But here’s what I noticed over 34 years of reading the fine print.
The richest investors in America own them. Quietly.
Leon Cooperman. David Tepper. Mario Gabelli. Men who run billions. Their own filings show it in black and white.
On TV they talk stocks. In their own accounts, they own American Income Partnerships. And they have for years.
Back when I started on Wall Street in 1992, I didn’t get it either.
I was a stock guy. I loved digging into a company. Reading about the town it was in, the people who worked there, the things they made.
I thought stocks were the only game worth playing.
So when I saw the smartest money on earth piling into something this plain and boring, it didn’t add up.
I had to know why. So I did what I always do. I dug in. I read every filing I could get my hands on.
What I found changed how I invest my own money.
Some of the guys I came up with still laugh about it. "No action," they say.
They’re right. There’s no action. That’s the point. Action is what took half their clients’ savings in 2008.
I’ve spent the years since sharing what I found with regular folks at Behind the Markets. People who are tired of being the mark. People like you.
A Check Every 90 Days Beats Worrying About a Highflyer
And I’ve never gone back.
Think about it. Do I really want to pay $337 a share for Apple... so I can maybe make $3,200 on a $10,000 stake if the stock cooperates?
No thanks.
I’d rather own an American Income Partnership and collect about $700 in cash. Cash that showed up on the day it was announced. No "maybe" about it.
There are so many famous stocks I won’t touch with a ten-foot pole.
Intel. One of the biggest names in America. It lost more than half its value in 2024 — and then stopped paying its dividend. Cut to zero.
That’s $6,000 gone for every $10,000 folks put into a "safe" blue chip like Intel. And no more checks.
Meanwhile, the income partnerships I follow...
...kept right on paying. About $700 that year on a $10,000 stake. Same as the year before.
Or look at the green energy stocks. For years, people were told those were the future. The safe bet.
They weren’t.
SunPower was one of the biggest solar companies in the country. In 2024, it went broke. The stock went to zero.
Picture losing all $10,000. Every dollar.
Even the "future" isn’t safe. This market makes no sense.
Now picture what those same folks could have done instead. Put that money into an American Income Partnership back in 2016...
...and collected about $5,200 in cash over those eight years. While SunPower was going to zero.
And they’d still own the partnership today.
It really is that simple.
Stocks up? You get paid.
Stocks down? You get paid.
You never have to sit through that sick feeling in your gut, wondering what your stocks will do tomorrow.
Because before you buy into one of these partnerships, the company has already told you what the next check is. How much. And what day it comes.
So ask yourself...
How much will the stocks in your account pay you this year?
You don’t know. Nobody knows. You can only hope.
And hope is not a plan. Not if you want to retire and stay retired.
What I Told My Family at the Kitchen Table in 2006
Let me tell you about the day I learned the difference between guessing and knowing.
It was June of 2006. Home prices were flying. Every guy on TV said the party would never end.
I looked at the numbers and saw something else. So I wrote it down and put my name on it.
“The market has no place else to go but down. It’s not a question of ‘if’ it’s a question of ‘when.’”
Then I did something most people on Wall Street never do. I sat my whole family down at the kitchen table.
My brother. My uncle. Yes, and even my in-laws. I told them a crash was coming and we had about a year to get ready.
Nobody guessed that day. We made a plan.
A year later, the market fell 43%. People I knew lost half of everything. My family didn’t.
I think about that kitchen table all the time...
Because when I ask people about their retirement, you know the first words out of their mouth?
"Well, I think I’m in pretty good shape."
They think. They hope. They guess. And I want to sit every one of them down at that table.
It doesn’t matter where you are...
Just getting started... or sitting on a big pile of savings...
You need a plan. Guessing is not a plan.
But guessing is all the stock market lets you do!
And the sharks on Wall Street love it. They get their cut whether you win or lose.
So here’s what I’d ask you to think hard about...
Are you tired of owning good companies and watching Wall Street punish them because profits missed by a penny?
Are you sick of losing money because some Fed official opened his mouth on TV?
Are you done watching the market climb just high enough to make you feel safe... and then fall apart like it did in 2001, 2008 and 2020?
Are you ready to stop rolling the dice?
I was.
And once I found American Income Partnerships, it took my game to a whole new level.
Just from the examples I’ve shown you today, a $10,000 stake in each would have paid you more than $22,000 in cash.
And I’ve got plenty more to show you.
Put together, at today’s payout rates, a $500,000 account spread across them could bring in about $35,000 a year. One check every month.
And the money won’t make you wait. Own the first partnership by October 30 and your first check lands around November 13.
Just do one thing for me first...
Only for People Who Want Steady, Boring Income
Don’t make the mistake of calling this money "dull."
Buffett said it best. The stock market moves money from people who can’t sit still to people who can.
The checks I’m talking about show up on a set day, four times a year, like the mailman. Same amount or more. Every time.
And you know what? Some people yawn at that.
But if dull means a check I can count on... from a company that has to get paid before it pays me...
Then I’ll take dull. Every day of the week and twice on Sunday.
And I’m far from the only one.
I have listened to pitches for the last two years and you are the only one that is real.
You are honest and care for your clients’ success.
And why wouldn’t they be happy? It’s the same check, on the same day, with nothing to guess about.
No wild swings. No sick feeling on Monday morning. None of it.
Now, all of this money comes from one place...
And I hope you’re not scared off by the "P" word.
I Hope You’re Not Scared Off by the “P” Word
I say that because in about ten seconds, I know the thrill-seekers are going to head for the door.
Thrill-seekers are the folks who invest for the rush.
The rush of maybe hitting it big... and the risk of losing just as big.
As for me, I’m 54. I’ve lived through three crashes. I don’t need the rush anymore.
The older I get, the more I like money that shows up.
And nothing shows up more like clockwork than the kind of company I’ve been showing you all along.
I’m talking about partnerships.
Not stocks. Not bonds. Not funds. Partnerships. When you buy in, you’re not a shareholder. You’re a partner in the business.
Now, if you need to leave because I said the word "partnership," I understand. Go ahead.
No hard feelings.
That’s the look I usually get. "A partnership? Isn’t that complicated? Isn’t that for rich guys?
Most people think a partnership is something you sign at a lawyer’s office. Or some private deal for the country-club crowd.
They’re wrong.
The ones I’m talking about trade on the New York Stock Exchange.
You buy them the same way you buy a stock. And I’d bet not one of those doubters has ever owned one.
Yes, some partnerships are risky. The ones that bet on prices. The ones loaded with debt. We saw a few of those cut their checks in 2020. I’ll come back to that.
And yes, some private partnerships are for rich guys only.
But American Income Partnerships work differently.
Their customers sign long deals to use equipment they can’t run their business without. And the customer pays for it, month after month, whether business is good or bad.
When the customer is booming, the partnership gets paid. When the customer is hurting, the partnership gets paid.
When the customer goes broke, the contract still gets paid first. You saw that with Chesapeake.
And because they’re set up as partnerships, not corporations, they can pass more of that money straight to you.
That’s why they can pay 6 to 8 times what the average stock pays.
And I haven’t even mentioned the price yet.
The first partnership I showed you has more than doubled since the spring of 2020.
On top of the checks.
I don’t count on that — the price fell by half on the way there, and it can fall again. But when the checks keep coming, the price tends to follow.
Here’s the part that matters most. Before you buy, the partnership has already told the world what the next check is. The amount. The day. It’s public.
The best of them have not missed a check in more than 25 years. Not one. And they’ve raised it for 27 years running.
If a check you can see coming, from a company that gets paid whether its customers are up or down, doesn’t sound good to you... I don’t know what to tell you.
But before you go, take one more look at what you’d be walking away from...
And there’s a clock on this. The first partnership on that calendar closes its list on October 30. Own it by then and the November 13 check has your name on it. Miss it, and you wait until February.
Because if you can type in a stock ticker and live with all the guessing that comes with it...
Then you can type in one of these tickers... and know what the next check is before you spend a dime.
For those of you still reading, good. You’re the kind of person this is for. Now let me walk you through exactly how it works... and how soon your first check can arrive.
A Check Every 30 Days, From Partnerships That Tell You the Amount in Advance
Like I said, American Income Partnerships are a special kind of company.
Not the kind where you buy and wait 20 years to see if it worked.
These pay you four times a year. Own a handful with different pay dates and you get a check every single month. Twelve a year. That’s how I set it up for my readers.
And the way it works is simple.
They trade on the New York Stock Exchange, right next to stocks. Same account. Same buy button. Same kind of ticker.
Let’s go back to that first partnership I showed you. The one Chesapeake was paying while it went broke.
Say you put in $10,000. At today’s price, that buys you about 320 units. (A unit is a partnership’s version of a share.)
Same as buying 320 shares of anything. Your money goes in.
Now here’s the part a stock can never do.
Before you buy one unit, the partnership has already told the world what your next check will be. How much per unit. And the exact day it lands.
Right now that check is about 54 cents a unit. Your 320 units would collect about $174 on the next pay date.
Four times a year. About $700 on your $10,000. Call it 7%.
And here’s what the check has done over time...
This partnership has paid it every single quarter since 1998. More than 110 quarters in a row. And it has raised it 27 years running.
Through the dot-com crash. Through 2008. Through Covid. Not one miss.
Now, the price bounced around plenty in those years. Some years up, some years down. You can lose money if you sell at the wrong time. I won’t pretend otherwise.
But the checks didn’t bounce. They went one way. Up.
So how can a partnership pay 7% when a normal stock pays 1%?
Here’s the trick. And it’s all out in the open.
When a normal company earns a dollar, Uncle Sam takes 21 cents first. Then the company pays you from what’s left. Then you pay tax again on that. Two bites.
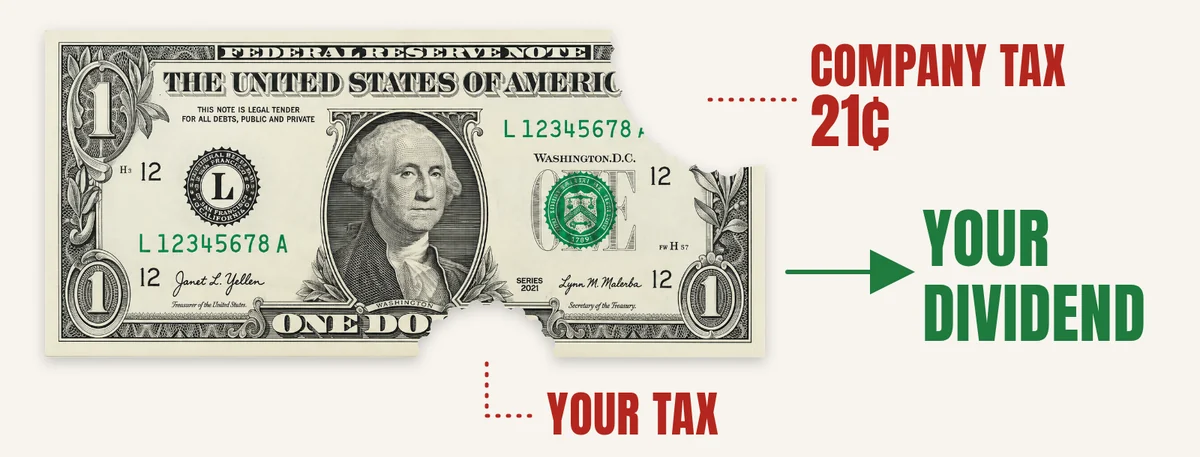
These partnerships skip the first bite. They pay no company tax at all. The whole dollar is there when your check gets cut.
That’s the deal they made with the IRS back in 1987. No tax on the company. In return, they can only earn money from a short list of plain, steady businesses. No side bets. The government pays them to stay boring.
Now here’s something you need to know before you go any further. Because they’re partnerships, you get a tax form called a K-1 each spring instead of a 1099. It comes a little later than your other forms, and your tax preparer will want it. That’s the paperwork your broker warned you about.
Here’s why I don’t mind it. Most of your check comes to you marked "return of capital." That means you get the cash now and the tax on it waits. Often for years. The K-1 is the receipt for the bite that never happened.
Now let me be straight with you about the other side.
A check is not a promise. That’s why I don’t buy just any of them.
I look for three things.
- Customers big enough to pay no matter what — the kind with better credit than most countries.
- Deals that pay whether the customer uses the equipment or not.
- And cash that covers the check with room to spare. This one earns about $1.70 for every $1.00 it sends out.
Do that, and you get what stocks can’t give you. A check you can see coming.
Look at the second partnership I showed you.
It pays about 9% today. And it has raised the check every year for the last five. While Paramount was cutting its dividend 79%.
Which would you rather have? A famous stock that cut your income by four-fifths... or a partnership that raised yours five years straight?
And who else invests this way?
Leon Cooperman owns the first partnership I showed you. So does David Tepper. Mario Gabelli too. It’s all in their filings. Men who run billions, quietly collecting the same checks I’m showing you.
We are in good company.
These men know how to make money. And not one of them ran when he heard the word "partnership."
Neither should you. Not when it can mean a check every month of the year.
You Could Have Cashed Every Check - And Almost Doubled Your Money on the Shares
I’ve spent this whole letter talking about checks.
Let me talk about the price for a minute. Because Wall Street has told you a lie about boring companies. That boring means no growth.
Here’s what actually happened.
Over the last five years, these partnerships, as a group, returned about 21% a year. With the checks put back to work.
The whole stock market over the same five years? About 12.6% a year.
Boring beat the market. And not by a little.
Put that in dollars. $10,000 in the market five years ago is worth about $18,000 today.
The same $10,000 in these partnerships? About $26,000.
And that’s the average. Look at the two I showed you.
Partnership #1 — the one Chesapeake was paying — turned $10,000 into about $21,400. It more than doubled.
Partnership #2 turned $10,000 into about $31,000. It tripled. Up 21% in 2022, the year the market lost 18%. Up 22% in 2023. Up 42% in 2024. Up 21% in 2025.
Now, those numbers count the checks, reinvested. Take the checks out and spend them, and the price alone still climbed more than 80% on both.
So you could have cashed every check... and still nearly doubled your money on the price.
Why does this happen? Simple. When a company raises its check 27 years in a row, buyers show up. The check is what you buy. The price is what you get for being patient.
That’s the last five years. Prices move, and they can move down. Past results don’t promise future ones. But nobody on TV ever told you that boring beat the market by eight points a year.
Now take a look at what’s sitting on the table right now...
Here Are the Checks I’m Targeting Right Now
Checks of every size. From partnerships of every size.
Checks of $600 a year and up, on every $10,000...
More than a dozen companies paying $700 a year or better.
A few paying $1,000 and more.
Every company on that list has passed my three tests. Big customers who have to pay. Deals that pay whether product moves or not. And cash that covers the check with room to spare.
I’ve been doing this kind of digging for 34 years. Since 1992.
And I’ve walked plenty of regular folks through it before you.
We are currently spending some of the gains made with your recommendations in Cancun. Thank you again for your timely reports and alerts.
This is the most valuable service I ever purchased.
What makes you special, and why I am a loyal supporter, is that your recommendations are based on logic and research.
In a moment, I’ll show you how you can join them.
Like I told you, your broker isn’t going to bring these up. Ask him why and he’ll say, "Oh, the tax form is a pain." That’s the excuse. You know the real reason now.
The big funds can’t load up on them. The brokers don’t get paid on them. So they stay quiet.
Today, the quiet ends.
I’ve put everything into one plain-English guide. It’s called "12 Checks a Year: The American Income Partnerships Guide."
Inside, you get every company on that list. The ticker. What it pays. The day it pays. And how to set them up so a check lands every month of the year.
The $35,000 a year I mentioned is just the starting line. On a bigger account, the checks grow with it.
And this isn’t hard. If you can buy a share of stock, you can buy into one of these. Same screen. Same button.
With this guide in your hands, you won’t have to guess at a single thing.
But there’s only one way I can get it to you today.
You have to try Behind the Markets.
Join Me and I’ll Show You Which Check Comes Next
I’d love to just hand you the list and wish you luck. But I’ve learned that doesn’t work.
I’ve watched too many people take one good idea, go it alone, and get lost.
Picture it. If I gave you a name today and walked away...
How would I be any better than the guy with the buzzers on TV? Or the broker selling you a 7% sales load and calling it a plan?
A tip is not a plan. A name is not a system.
Real help means being there next month. And the month after that. When the check comes in, and when a question comes up.
So every month, I’ll be in your inbox with a full issue. New partnerships that pass the three tests. Any that stop passing. And what to do about it. And if something changes in between, you get an alert the same day.
Here’s how Behind the Markets works. It’s simple.
Once a month, you get a full issue from me. Plus alerts whenever something changes. Like this one.
It tells you what to buy, the price to pay, what the company has declared for its next check, and the day that check lands.
You’ll know all of that before you spend a dollar. That’s what makes American Income Partnerships different.
Stocks can’t do that. Nobody can tell you what a stock will pay you next quarter. Nobody.
That’s the whole point of Behind the Markets.
You know the next check before you buy. No surprises on pay day.
And that’s why my readers stick around.
You’re the only person I trust.
The most accurate advisor I’ve ever used. Far above all other services in integrity.
They trust me with their retirement. I don’t take that lightly. And I’ll earn yours the same way.
One more thing. The worries that come with stocks? Most of them don’t apply here. Let me show you why.
We Only Recommend Partnerships That Pass Three Tests
American Income Partnerships I pick don’t work that way.
They charge a fee. The fee is set by contract. Good year or bad year for the customer — the fee is the fee.
And here’s a part most people miss. Many of those fees go up every year with inflation. It’s written right into the deal.
That’s the edge. When prices at the store go up, the fee goes up. Your check goes up with it.
Now, will the price move? Of course. In 2015 and again in 2020, these got hit hard — the good ones and the bad ones alike. That’s the risk, and I won’t hide it.
But look at what happened next. The ones that kept paying more than doubled in five years. The check is what you buy. The price is what you get for being patient.
Now you might be wondering, is this some new thing? Some fad?
Just the opposite. The partnership I showed you first has paid every quarter since 1998. These have been around longer than most of the stocks in your account.
They just don’t get talked about. The big funds can’t load up on them. Brokers don’t get paid on them. So they sit quietly and pay their partners.
And like I showed you with Chesapeake, when a customer goes broke, the contract still gets paid. That’s what a contract is for.
Now, could the partnership itself go under?
That’s the one way you wouldn’t get your check.
But think about that. If you owned a stock and the company went broke, you’d get nothing either.
The partnerships I pick have some of the biggest customers on earth, contracts that run for years, and cash to spare after every check. I do that homework so you don’t have to.
And the ones that cut in 2020? Not one of them would pass my three tests today.
So it comes down to this...
Behind the Markets gives you the best of both worlds.
You get paid when the economy is up.
You get paid when it’s down.
The fee is set by contract with the biggest companies in America.
You get a kind of steadiness no stock owner can claim.
And trust me, your friends will want to know how you did it...
My Readers Send Me Notes Every Week About the Checks That Just Landed
I can say that because almost every week, a reader sends me a note about a check that just landed.
I love those notes. Keep them coming.
Thanks so much, I am a real Dylan Jovine believer.
A lot of my readers came up the hard way, like I did.
Honest & intellectual service.
Like you, these folks wanted to make real money without lying awake wondering if it would be gone by morning.
I could go on for pages about the checks my readers have collected. You’d get bored before I ran out.
So instead, let me just send you the guide. "12 Checks a Year: The American Income Partnerships Guide."
And listen. If you can type in a stock ticker and live with all the guessing that comes with it...
Then you can type in one of these tickers and collect a check the company already told you about.
No guessing. No wondering if it comes.
Not a bit of it.
Following Behind the Markets should feel like the most boring money you’ve ever made. And I mean that as the best thing I can say.
That’s the whole story.
Join Behind the Markets Today for Just $49 — 88% Off
Now, here’s what it costs. And I think you’ll like this part.
A full year of Behind the Markets normally sells for $399.
For that, you get twelve monthly issues. My full model portfolio. Every sell alert the moment something changes. A members-only website. And a VIP concierge line you can call Monday through Friday, nine to five, and reach a real person.
Members who pay $399 tell me it’s worth every penny. And I agree.
But you’re not going to pay $399.
Not $299. Not $199. Not even $99.
Because I’ve read this far with you, and I know what you’re after. You’re not chasing a hot tip. You’re trying to protect what you spent a lifetime saving — and get paid for it.
So I’m going to make this as easy as I possibly can.
You can join Behind the Markets today for just $49.
That’s for the whole year. Not per month. One payment of $49, and you’re in for twelve months.
That’s 88% off what everyone else pays.
Why so cheap? Simple. I sat my own family down at a kitchen table once and told them what was coming. I’d like to do the same for you, and I don’t want price to be the reason you don’t sit down.
And $49 is less than one check from a $10,000 stake in a single partnership. The membership can pay for itself with the first envelope.
There’s no catch. No add-on fees. No surprise renewal you didn’t agree to.
You’ll get every issue, every pick, and every alert for the full year. Your checks stay on track and so do you.
And you get my 6-month guarantee on top of that.
Try everything for 6 months. Read the guides. Watch the video. Set up your first partnership if you like.
If it’s not for you, call the concierge line and you get every dollar back. No questions. No hassle.
And you keep both guides and the video. Even if you cancel.
I plan to show you a check or two before those 6 months are up.
Try It for 6 Months. Keep Every Check. No Strings.
I’ll keep the checks coming your way.
All you have to do is give Behind the Markets a try.
Every month you’ll hear from me about a partnership that’s already told you what it will pay, and when.
Here’s what a full year of checks looks like when the picks in my guide are set up the way I show you...
Twelve checks. Twelve months. Each one announced before it comes. How big they are depends on how much you put in — that part is up to you. Picture what your mailbox looks like a year from now.
And by now you know I’m not one of the smiling men with a license. I can’t stand those guys.
So yes. Take the guide, "12 Checks a Year." And take the full 6 months to try it out.
Collect every check you can. And keep the guide, even if you decide this isn’t for you.
Actually, I can do better than that...
I’ll Show You Five Checks That Could Pay You Back for Joining
I like it when something I buy pays me back.
I have a feeling you’re built the same way.
So you get a second guide when you join today.
And this is the one to read first.
It’s called "The Payback List: Five Checks That Could Cover Your Membership in Year One."
Inside are the five biggest payers on my list. Own them the way I show you, and at today’s rates, the checks could add up to more than you paid to join — in the first year.
So that $49? Think of it as money you get back, a check at a time.
I can’t think of a better way to start.
So now you’re getting two guides:
"12 Checks a Year: The American Income Partnerships Guide"
"The Payback List: Five Checks That Could Cover Your Membership in Year One"
I can’t wait for you to know what your next check is before it lands.
And even if you’ve never bought into a partnership in your life — even if that K-1 form scares you — I’ll get you up to speed in nine minutes flat...
I’ll Walk You Through Your First American Income Partnership in 3 Minutes
I sat down and filmed a short video that takes you through the whole thing, start to finish.
On screen, you’ll see a plain brokerage account. The same kind you already have.
I’ll type in a ticker... I’ll show you where the company posts its next check and pay date... and I’ll hit "buy" right there so you can watch it happen.
Then I’ll show you the K-1. What it looks like when it comes. What to hand your tax person. And why it’s good news, not bad.
If you’ve never owned an American Income Partnership, this is your training wheels.
Watch it again any time you buy, so you know you did it right.
And if you’ve done this before, it’s a good refresher.
The video is called "How to Buy Your First American Income Partnership (and Read Your K-1) in Nine Minutes."
So let me pull it all together and get you started.
Join Today and You’ll Get:
✓ 6 Months to Try It Out...
✓ A Plan for 12 Checks a Year — One Every Month...
✓ Five Picks That Could Pay You Back for Joining...
✓ And the Nine-Minute Video That Shows You Every Step
Join today and you get two guides, one video, and a full issue from me every month:
- "12 Checks a Year: The American Income Partnerships Guide"
- "The Payback List: Five Checks That Could Cover Your Membership in Year One"
- "How to Buy Your First American Income Partnership (and Read Your K-1) in Nine Minutes"
Wall Street bought the houses out from under a whole generation and rented them back to us. I can’t undo that. But I can help make sure they don’t do it to your savings.
Sincerely,
Dylan Jovine